As the tax year draws to a close, real estate investors often find themselves scrambling to reconstruct property-related expenses from bank statements and inboxes. According to CostSegRx, an engineering-based cost segregation firm, this last-minute approach can lead to lost details that significantly affect depreciation and tax outcomes. “Property owners should really document all of their capital improvements and expenses throughout the year,” said Brian Kiczula of CostSegRx. “It’s not just at the year-end.” The goal is not a perfect filing system but a clear record of what work was done, when it was completed, and what it cost.
Many investors mistakenly lump all property costs together and attempt to expense them immediately. However, tax treatment differs for capital improvements versus repairs. When a CPA or cost segregation professional reviews spending, they typically apply the BAR test—betterment, adaptation, or restoration—to determine whether a cost must be capitalized. Capitalized costs are depreciated over 27.5 years for residential rental property, 39 years for commercial property, or shorter lives of 15, 7, or 5 years depending on the asset. Costs that fail the BAR test usually qualify as repairs and maintenance, deductible in the year incurred. Without proper records, distinguishing between these categories becomes unreliable, potentially costing investors valuable deductions.
In CostSegRx’s experience, the most common documentation gaps involve individual receipts and clear descriptions of work performed. Owners tend to fall into two groups: those who meticulously track every improvement with dates and receipts in spreadsheets, and those who know only a rough annual total without a breakdown among flooring, windows, lighting, or other components. The latter group is often not at fault, as many contractors bill in lump sums without itemizing costs. For such owners, CostSegRx uses construction cost estimating to rebuild contractor costs from descriptions and images, allowing each improvement to be properly classified. Simple habits—saving receipts, noting what was done, recording completion dates, and photographing finished work—can make a substantial difference going forward.
Timing also matters when a property is acquired and renovated in the same year. If renovations are completed before the property is placed into service, the original cost segregation study may need adjustment. For example, replacing all carpet before placing a building in service means the old carpet had no value and should be removed from the purchase price allocation, with the new carpet added. If the property is placed in service first and a major remodel follows, the tax preparer typically receives two separate fixed asset schedules—one for the acquisition and one for the remodel. This pattern is common with hotels, where owners acquire a property and begin updating rooms the following year.
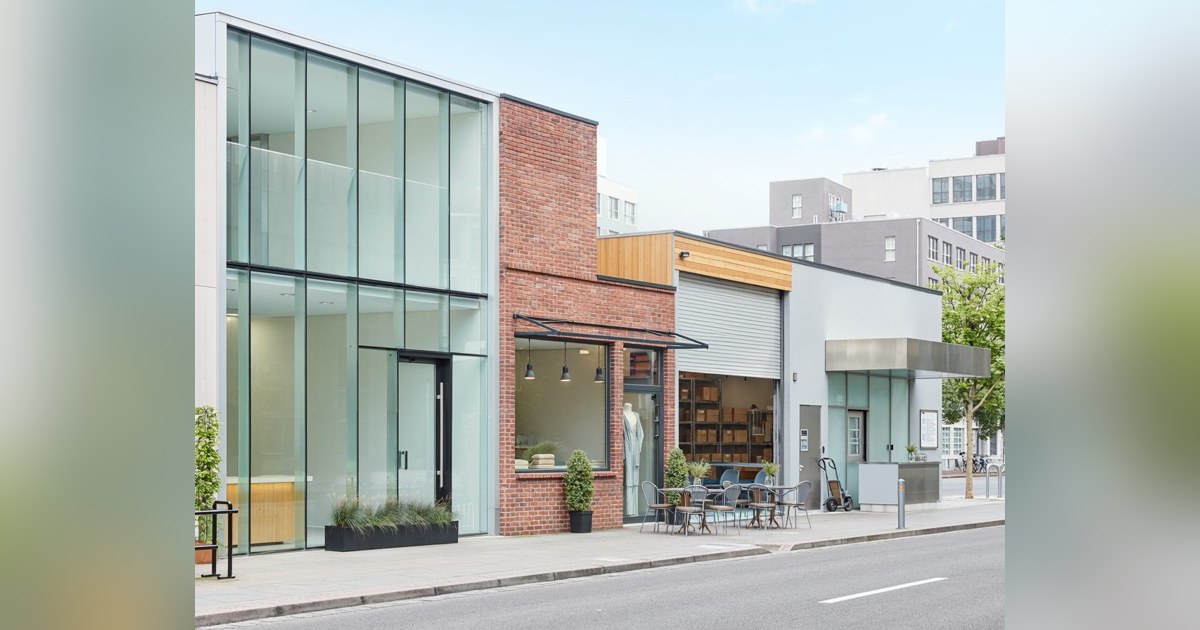
Disorganization is common among landlords, who are busy running their properties without a dedicated team tracking every expense. However, it is rarely too late to get organized. CostSegRx recently completed a study on a multi-year renovation of three buildings—a restaurant, a boutique bed and breakfast, and a group of shops—where the owner lacked original construction data, yet the team still produced a quality study. As long as an owner can document that improvements were made, a study can usually still be performed. The practical takeaway is to stop treating documentation as a year-end task. Keeping records as work happens, sharing them with a CPA, and asking early how renovations will be classified can help investors avoid missed opportunities and ensure compliance with tax rules.