Texas drivers who carry the state's minimum auto liability insurance may believe they are fully protected after a crash, but a serious injury can expose them to tens of thousands of dollars in unexpected costs. The state's minimum coverage requirements have not increased since 2011, even as medical expenses and other accident-related costs have climbed, leaving a widening gap between what policies pay and what injuries actually cost.
Under Texas law, drivers must carry liability coverage of $30,000 for injuries to one person, $60,000 for injuries per accident and $25,000 for property damage, known as 30/60/25 coverage. These amounts are legal minimums, not necessarily adequate protection. According to a 2023 report from the National Highway Traffic Safety Administration, the estimated average lifetime medical cost of a serious crash injury was $69,345, while the total economic cost reached $280,726, based on 2019-dollar estimates. That total economic cost is more than nine times Texas's $30,000 minimum bodily injury liability limit.
Once an at-fault driver's liability insurance reaches its policy limit, that coverage generally will not pay additional expenses, even as medical bills, lost income and rehabilitation costs continue to grow. The risk escalates when the responsible driver has little or no insurance. Research cited by the Insurance Research Council found that approximately one-third of U.S. drivers were uninsured or underinsured in 2023, meaning even a not-at-fault driver may find the other party's coverage insufficient to compensate everyone injured.
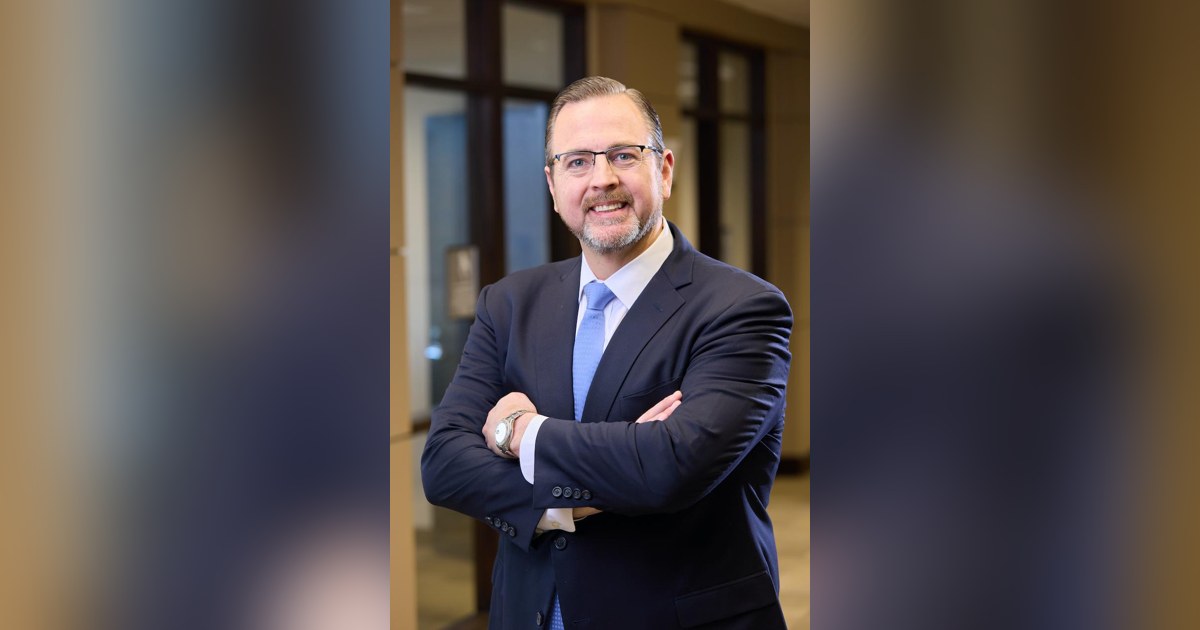
Ryan L. Thompson, founder and managing partner of Thompson Law, also known as 1-800-LION-LAW, understands these challenges from both sides of the legal process. Before representing injured individuals, Thompson spent years defending major corporations, gaining firsthand experience with how insurance claims are evaluated and resolved.
One protection many drivers overlook is uninsured and underinsured motorist coverage, commonly known as UM/UIM. This coverage can help eligible policyholders recover certain expenses when an at-fault driver has no insurance or insufficient liability coverage. Texas law generally requires insurers to include UM/UIM coverage in auto policies unless the policyholder rejects it in writing. However, drivers may decline this protection to reduce premiums without fully considering the potential financial consequences.
Thompson Law encourages drivers to review their insurance declarations page, which summarizes coverage types, limits and deductibles. Drivers should check whether their liability limits are adequate, whether they carry UM/UIM coverage and whether additional protection makes sense for their circumstances. The Dallas-based personal injury firm, founded by Thompson, reports recovering more than $2.1 billion for injured people and families nationwide as of August 2026.
The message for drivers is simple: Meeting the state's minimum insurance requirements does not necessarily mean you are fully protected. Taking a few minutes to understand your policy today could make a significant financial difference tomorrow.