
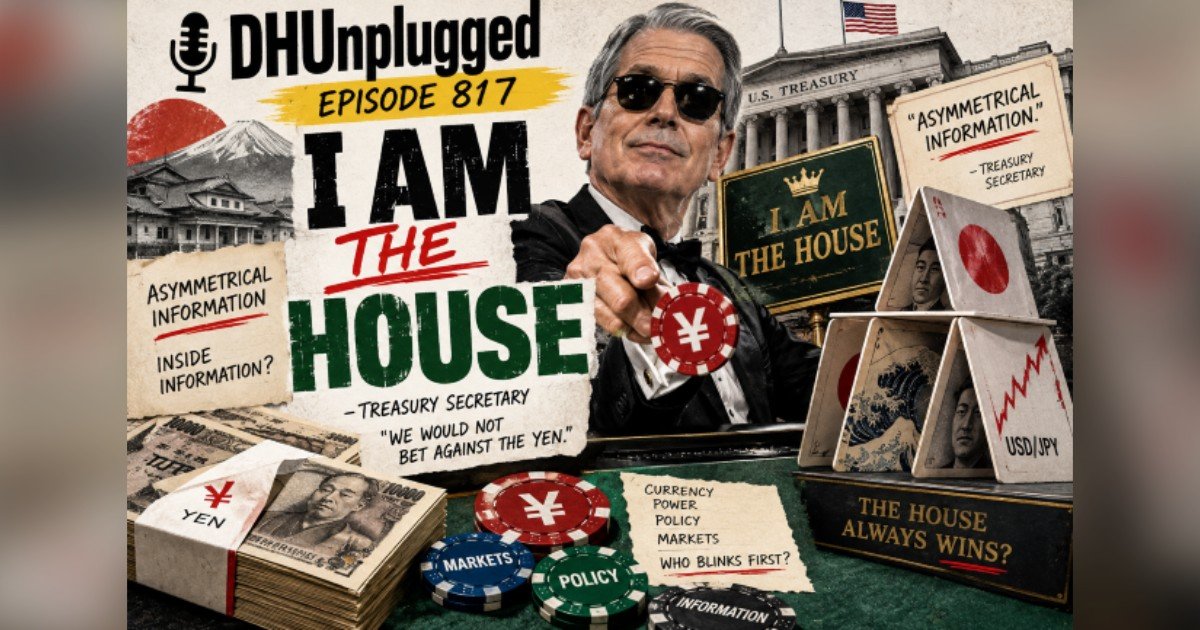
The post-Labor Day trading session delivered a stark reminder of the fragility of current market conditions, with the Dow Jones Industrial Average plunging more than 600 points. Yet the most consequential development may have been a comment from Treasury Secretary Scott Bessent, who openly declared that he possesses inside information on the Japanese yen. The remark, made during a period of heightened volatility, has been interpreted by market analysts as a watershed moment in the relationship between policymakers and financial markets.
On Episode 817 of the podcast DH Unplugged, hosts Andrew Horowitz and JC Dvorak dissected Bessent’s statement, framing it as an unprecedented acknowledgment that the government now operates as 'the house' in financial markets. Horowitz highlighted Bessent’s phrasing: 'I have the inside information about what Japan is doing, therefore when I say something, it's not going to be speculative. It's going to be absolute.' Dvorak placed the comment in historical context, arguing that since the 2008 financial crisis, the government has increasingly behaved like the Roman Senate before Caesar, with the Trump era making the dynamic impossible to ignore.
The episode arrives at a critical juncture for markets. With a Consumer Price Index (CPI) report scheduled for Friday, strategists are calling it the ultimate credibility test for the Federal Reserve. The selloff, combined with rising Treasury yields, has intensified scrutiny on the Fed’s ability to manage inflation without derailing economic growth. The hosts also noted a series of other market-moving events, including a 'dead-quiet' Strait of Hormuz according to AIS trackers, which has fueled speculation about oil supply disruptions. Goldman Sachs has set a $120 per barrel oil target, adding to concerns about inflationary pressures.
Bond markets are flashing warning signs, with 10-year and 30-year Treasury yields climbing against a backdrop of a $40 trillion national debt. Horowitz explained that his firm is purchasing only short-duration Treasuries, citing the crush of new issuance from Washington and from data center operators tapping capital markets globally. This cautious approach reflects broader unease about the sustainability of fiscal policy and its impact on long-term yields.
The episode also covered Meta’s approximately $18 billion multi-state settlement over youth safety guardrails, a landmark agreement that could reshape social media regulation. In the tech sector, NVIDIA’s reported $13 billion acquisition of Hugging Face—which JC had predicted a week earlier—signals continued consolidation in the AI space. The hosts also touched on Bloom Energy’s addition to the S&P 500, which sparked sympathy rallies in Oklo and other small modular reactor (SMR) stocks, as well as strength in Intel, AMD, and SK Hynix ahead of Broadcom earnings.
Other threads included Shein’s downsized Hong Kong IPO, Good Good Golf’s Callaway ad backlash, Nike’s exit from the S&P 500, Argentina beef imports, a 162,000 payrolls print, and Astra’s partial Navier-Stokes proof. The hosts’ skeptical, unfiltered tone was on full display as they navigated these topics, offering listeners a comprehensive view of the week’s most consequential stories.
As the markets brace for the CPI print, the implications of Bessent’s remarks loom large. If policymakers are indeed playing the market as 'the house,' the line between fiscal policy and market manipulation becomes increasingly blurred. The episode underscores the urgency of understanding these dynamics, as investors navigate a landscape shaped by political intervention and economic uncertainty.